Collateral Risk Assessment & Management
Complete Collateral Risk
Assessment & Management
Veros’ products and solutions work relentlessly to help you achieve more accurate and reliable collateral assessments to better control risk throughout the entire mortgage chain from origination through securitization of mortgage-backed and asset-backed securities pools. The result is a suite of tools that will change the way you view your real estate or lending portfolio, the way you think about risk management and the way you manage your workflow to keep up with the rapid pace of the mortgage industry.
Collateral Risk Management Solutions
When disaster strikes – be prepared with the parcel-level information on how much – if at all – a specific property was impacted by a hurricane, wildfire, earthquake, flood or other disaster. Veros Disaster Vision data is available as an add on when you choose VeroVALUE AVMs.
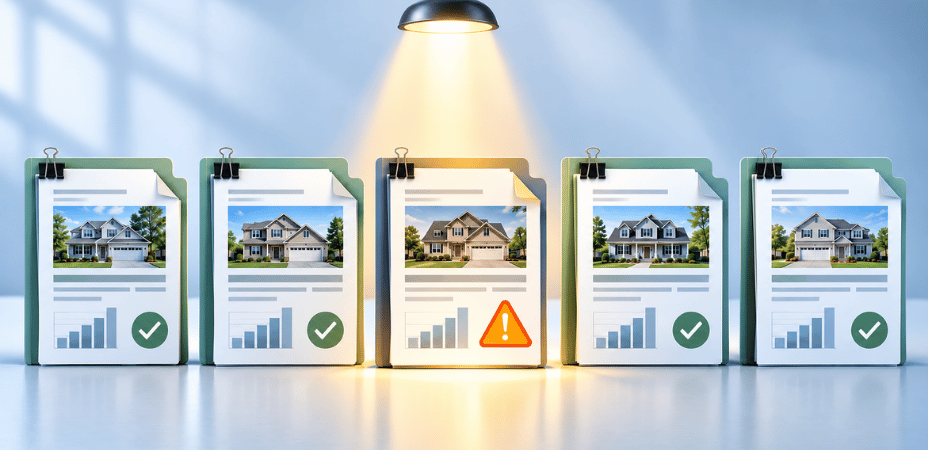
You’ll be able to make faster, more insightful and virtually instantaneous analysis of appraisal reports and their associated risk. VeroSCORE delivers concise, easy-to-apply corrective actions, replacing the complex, time-consuming manual appraisal review with immediate automated analysis and scoring. This significantly simplifies the review process and enables users to identify high-risk appraisals before they result in rejections or repurchase requests.
To Speak To Our Sales Team
866-458-3767 Option 2
Features

UAD 3.6 Appraisal Review: Prioritizing Higher-Risk Files
UAD 3.6 brings more structured appraisal information to the mortgage industry. The next opportunity is using that information to determine which files warrant deeper review.
Q4-2026 Quarterly Economic & Housing Market Update
Mortgage rates have climbed to 7.40%, inflation has accelerated to 3.7%, and hiring has slowed to just 29,000 jobs. Meanwhile, existing home sales remain below 4 million annually despite improving inventory. The problem is no longer simply a shortage of homes. It is the widening gap between what buyers can afford and what sellers are prepared to accept.
The Economics of Price Cuts: Why Sellers and Buyers May Prefer Concessions Over Lower Prices
Why are home sellers offering thousands of dollars in incentives instead of simply lowering their asking prices? Discover how closing-cost credits and mortgage-rate buydowns are reshaping negotiations, and why home prices may be weakening more than the numbers suggest.